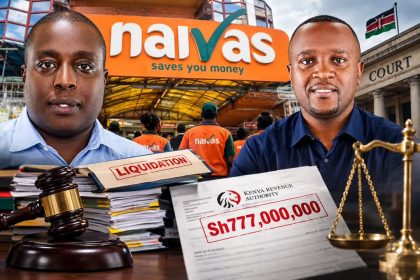

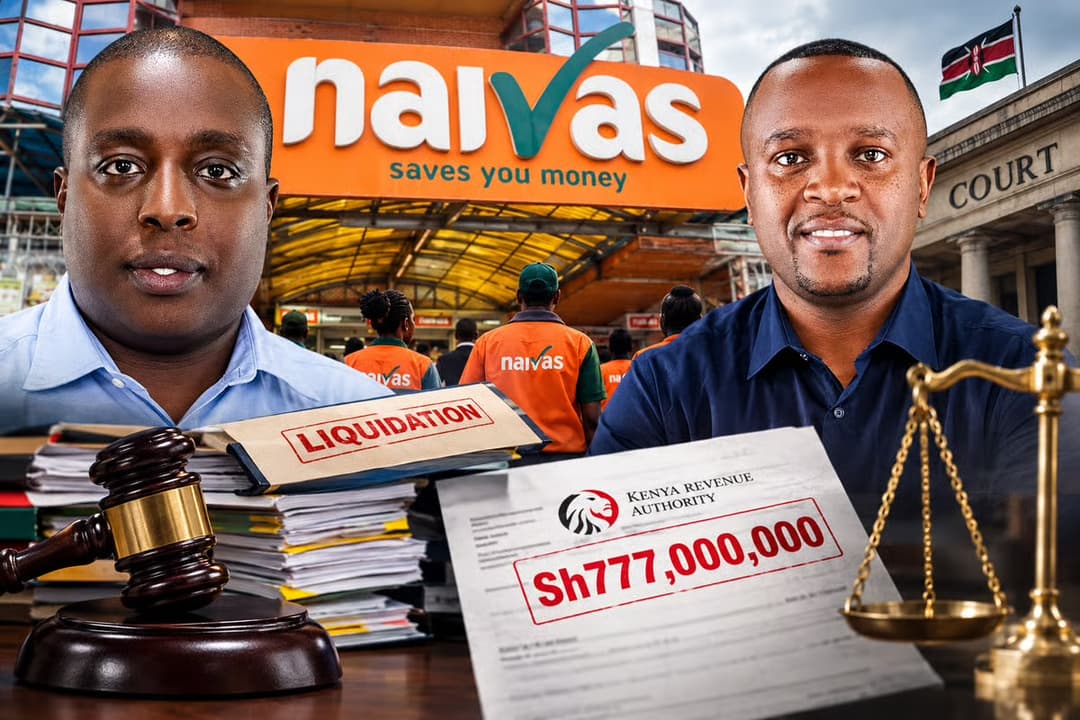
The High Court has set aside a Kenya Revenue Authority (KRA) Value Added Tax demand of about KSh 777 million against Achievo Limited, the human-resource outsourcing firm linked to Naivas supermarket operations and associated with Peter Mukuha Kago.
Key takeaway: The court held that salaries and related staff costs paid through Achievo for Naivas workers were agency disbursements under Section 13(5) of the VAT Act, not taxable turnover. The Tax Appeals Tribunal judgment of 2 May 2025 was set aside.
In Achievo Limited v Commissioner of Legal Services & Board Coordination [2026] KEHC 14253 (KLR), Justice Moses Ado of the High Court Commercial and Tax Division delivered judgment on 22 September 2026. Business Daily reported the outcome on 8 October 2026 as a win for the Naivas-linked firm and Mr Mukuha.
What KRA Assessed
After an audit covering 2019 to 2023, KRA issued additional assessments dated 26 February 2024 for:
- VAT: about KSh 777.09 million (confirmed figure after partial consent; original VAT assessment was higher, about KSh 962.7 million)
- Income tax: about KSh 102.13 million
KRA’s core VAT argument was that Achievo was the legal employer of the outsourced workers, so money received from Naivas for staff costs formed part of the taxable value of its services. In KRA’s view, VAT should apply on the gross amount, not only on any management fee or mark-up.
Achievo objected, saying it received and passed on staff wages and statutory remittances as agent of Naivas, without mark-up on those lines, and that it accounted for VAT on its separate agency or management fee.
Swipe left and right on mobile →
| Item | Detail |
|---|---|
| Parties | Achievo Limited v Commissioner of Legal Services & Board Coordination (KRA) |
| Court | High Court, Nairobi (Milimani Commercial & Tax), Justice Moses Ado |
| Judgment date | 22 September 2026 |
| Case | Tax Appeal E188 of 2025 / [2026] KEHC 14253 (KLR) |
| VAT at stake | About KSh 777,092,137 on staff-cost reimbursements |
| Audit period | 2019–2023 |
| Earlier TAT outcome | Tribunal dismissed Achievo’s appeal on 2 May 2025 (TAT E717 of 2024) |
Why the High Court Sided With Achievo
The central legal question was Section 13(5) of the VAT Act. That provision includes incidental costs in the taxable value of a service, but excludes amounts the Commissioner is satisfied are mere disbursements made by a supplier as agent of the client.
Justice Ado found that the Service Level Agreement and addendum between Achievo and Naivas were clear: direct costs, including staff wages and statutory remittances, were to be borne by Naivas. Payments Achievo made on those lines were recoverable as disbursements. Absent fraud or other vitiating factors, the court said the parties’ contractual allocation could not be recharacterised the way KRA had argued.
The court also noted Finance Act 2026 amendments that inserted Sections 13(5A) and 13(5B) into the VAT Act while the appeal was pending. Those provisions expressly exclude employee costs in labour-outsourcing arrangements from the taxable value of a supply. The judge treated them as reinforcing the same direction, not as the sole basis of the decision for the 2019–2023 years.
Orders issued included:
- Appeal allowed
- Tax Appeals Tribunal judgment of 2 May 2025 set aside
- KRA’s objection decision assessing VAT on staff-cost disbursements or reimbursements from Naivas vacated and set aside
- Each party to bear its own costs
How the Dispute Reached the High Court
Achievo is a private company registered for corporation tax, VAT and PAYE. Its main business, on the judgment record, is outsourced HR support to Naivas Limited, with association through common directorship.
After KRA’s assessment and objection process, the Tax Appeals Tribunal in May 2025 upheld KRA. The Tribunal held, in substance, that even if the contracts used agency language, Achievo had not proved, through bank statements or comparable evidence, that every staff-cost sum from Naivas was passed on in full to employees without deduction.
Achievo later obtained leave to appeal out of time and a stay of execution in April 2026. The High Court then heard the tax appeal on the merits and, in September 2026, reversed the Tribunal on the VAT treatment of those staff reimbursements.
Related Company-Register Case (Separate File)
Separately, Achievo was struck off the Companies Register under Gazette Notice No. 8218 published on 29 May 2026 for failing to file annual returns. Directors, including Peter Mukuha Kago, have sought restoration before the High Court in HCCOMMISC/E1022/2026, arguing that dissolution risked assets, accounts and ongoing payroll-related dealings.
That restoration application is not the same as the VAT judgment. The tax win deals with how staff-cost money should be treated for VAT. The strike-off fight deals with the company’s legal existence on the register. Readers should keep the two tracks distinct.
What the Ruling Means in Practice
For labour-outsourcing and payroll-agency models, the decision underscores that documentation matters: clear SLAs, separation of pure staff disbursements from taxable management fees, and evidence that money moves as the contracts say.
It does not mean every payment an HR firm receives is outside VAT. Amounts that are true fees for services remain taxable. The High Court’s orders specifically vacated VAT on the staff-cost reimbursements from Naivas that KRA had treated as taxable supply value.
Whether KRA appeals further is a separate step. As of reporting on 8 October 2026, the High Court outcome stands as published.
Claims that the ruling alone “saves more than 2,000 jobs” track advocacy language used in earlier affidavits when enforcement and company status were under pressure. The judgment itself is a tax-law decision on VAT and disbursements, not a labour-court order on employment numbers.
Read also:Naivas Owners Seek Court Order to Restore Achievo Limited
Bottom Line
On 22 September 2026 the High Court allowed Achievo Limited’s appeal, set aside the Tax Appeals Tribunal’s May 2025 judgment, and vacated KRA’s VAT assessment of about KSh 777 million on staff-cost reimbursements received from Naivas. The court treated those amounts as agency disbursements under Section 13(5) of the VAT Act, consistent with the SLA structure between the two firms.
Peter Mukuha Kago is associated with Achievo and the Naivas group. A separate application to restore Achievo to the Companies Register after a May 2026 strike-off remains a different legal track. Businesses using outsourced payroll should still separate taxable fees from pure reimbursements and keep proof of how funds move.
Sources: Kenya Law – Achievo Limited v Commissioner of Legal Services & Board Coordination [2026] KEHC 14253 (KLR) (22 September 2026); Business Daily – Naivas heir wins Sh777m tax dispute over HR firm (8 October 2026); Kenya Law – leave to appeal and stay ruling [2026] KEHC 5319 (KLR). This article is for information only and is not tax, legal or investment advice. Court outcomes can be appealed; confirm the latest status before relying on the decision.