
After two straight weeks of losses, the Nairobi Securities Exchange staged a sharp comeback. The week ending September 24, 2026 saw every major index rally hard, pushing market capitalisation firmly back above the KSh 4 trillion mark.
Total market value rose 5.61 percent during the week to close at KSh 4.17 trillion, according to the Central Bank of Kenya’s Weekly Bulletin released on Friday, September 25.
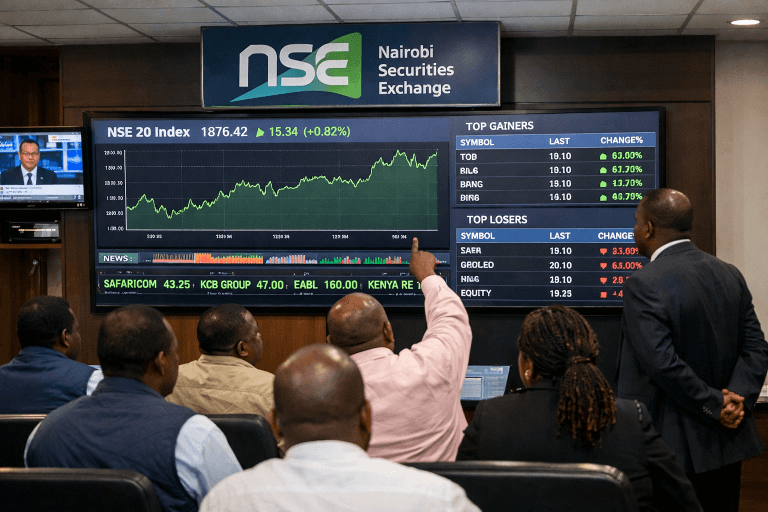
A Strong Week Across the Board
| Index | Weekly Change |
|---|---|
| NASI (NSE All Share Index) | +5.61% w/w |
| NSE 25 Share Index | +6.92% w/w |
| NSE 20 Share Index | +6.76% w/w |
| Market Capitalisation | +5.61% w/w to KSh 4.17 trillion |
The rally followed two consecutive weekly declines that had pulled the market below KSh 4 trillion in mid-September. This week’s gains more than reversed that slide, putting the Nairobi Securities Exchange back on firmer footing heading into October.
Money Markets Stayed Liquid
Kenya’s money market conditions remained supportive through the week. Commercial banks held average excess reserves of KSh 15.8 billion above the 3.25 percent cash reserve requirement, while the Kenya Shilling Overnight Interbank Average held steady at 8.75 percent.
Interbank activity also picked up, with the average number of daily transactions rising to 27 from 19 the previous week, and the average value traded increasing to KSh 14.5 billion from KSh 13.1 billion.
Bonds and Treasury Bills Also Rallied
Fixed income markets moved in step with equities. Secondary market bond turnover more than doubled, jumping 104 percent to KSh 71.2 billion, up sharply from KSh 34.9 billion the previous week.
The Treasury bill auction held on September 24 drew strong demand too, with investors submitting bids worth KSh 41.7 billion against KSh 28 billion on offer, a 149 percent performance.
Banks Enter Dividend Season
Several banking heavyweights hit their book closure dates for final dividends during the week, triggering the usual technical price adjustments. Standard Chartered Bank Kenya and Car & General both traded ex-dividend, while Absa Kenya and Co-operative Bank also saw downward pressure tied to dividend timelines.
A stock’s price typically dips by roughly the dividend amount once it goes ex-dividend, since the payout is no longer bundled into the share price for new buyers.
Friday’s Top Movers
| Company | Movement | Details |
|---|---|---|
| Centum Investment | Top Gainer | Rose 4.16% to close at KSh 18.80 |
| I&M Holdings | Gainer | Up 2.41% to close at KSh 85.00 |
| BK Group | Top Loser | Fell 5.31% to close at KSh 58.00 |
| Standard Chartered / Car & General | Lower | Declined following ex-dividend adjustments |
Foreign Investor Activity Stayed Mixed
Foreign participation swung both ways through the week. Monday opened with a modest KSh 3.32 million in net foreign buying, before flipping into net selling of KSh 44.80 million on Tuesday and KSh 10.82 million on Wednesday.
That pattern extends a run of inconsistent foreign positioning seen through September, following heavier net outflows during both of the month’s earlier corrections.
Read also:NSE Weekly: Market Sheds KSh206B as Stocks Fall 4.96% in One Week.
Bottom Line
This week’s rebound reversed two straight weeks of losses, pushing market capitalisation back above KSh 4 trillion and every major index into positive territory. Supportive money market conditions and strong demand at the Treasury bill auction added to the positive tone.
Dividend season is still working its way through the banking sector, so some of the technical price dips seen this week are likely to continue as more counters hit their book closure dates.
Sources:
Central Bank of Kenya Weekly Bulletin
Nairobi Securities Exchange