
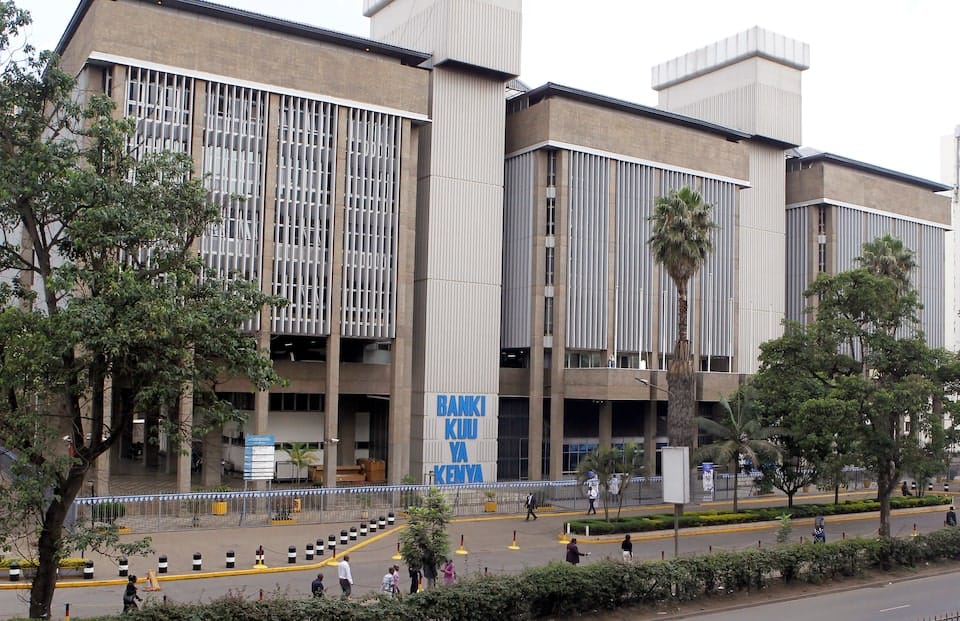
Seven commercial banks failed to hold the minimum core capital of KSh 3 billion in 2025, the Central Bank of Kenya (CBK) says in its Bank Supervision Annual Report 2025.
The breaches are measured as at 31 December 2025. CBK states the seven lenders violated Section 7(1) of the Banking Act by failing to maintain the statutory minimum core capital of KSh 3 billion.
The finding appears in the compliance section of the annual report and has been reported by local media on 22 September 2026 after the report’s release.
What Else the Report Found on Capital
Besides the absolute KSh 3 billion floor, several banks also missed ratio-based capital rules:
Mobile: Swipe left / right → ←
| Requirement | Threshold | Banks in breach (Dec 2025) |
|---|---|---|
| Minimum core capital (Banking Act s.7(1)) | KSh 3 billion | 7 |
| Total capital / risk-weighted assets | 14.5% | 5 |
| Core capital / risk-weighted assets | 10.5% | 4 |
| Core capital / total deposits | 8% | 3 |
← Swipe on mobile → Source: CBK Bank Supervision Annual Report 2025
These ratio breaches sit under Section 18 of the Banking Act and CBK Prudential Guideline on Capital Adequacy (CBK/PG/03), as set out in the same report.
Overall, CBK recorded 35 commercial banks in violation of the Banking Act and prudential guidelines as at 31 December 2025, up from 11 a year earlier. Many breaches related to risk-based credit pricing models, single-obligor limits and the new absolute capital minimum.
Sector Still Strong in Aggregate
The same report paints a healthier picture for the system as a whole.
Total capital adequacy stood at 20.7 percent in December 2025, above the 14.5 percent minimum. Core capital to risk-weighted assets was 18.2 percent, and core capital to deposits about 18.1 percent, both well clear of their floors.
Banking sector capital and reserves rose 18.6 percent to about KSh 1.40 trillion. Total net assets grew 10.3 percent to about KSh 8.35 trillion. Profit before tax increased to about KSh 306.3 billion.
In short: most of the industry is comfortably capitalised. The problem is concentrated in a small group of undercapitalised lenders, mainly smaller institutions.
Why the Sh3bn Rule Exists
Kenya raised the minimum core capital for commercial banks from the old KSh 1 billion floor under reforms linked to the Business Laws (Amendment) Act, 2024. The first hard step was KSh 3 billion by end-December 2025, as part of a longer path toward a much higher eventual minimum (commonly framed toward KSh 10 billion over multi-year stages).
The policy aim is thicker capital buffers, fewer fragile small banks and stronger capacity to absorb shocks. Lenders that cannot raise equity, attract investors or merge face pressure from the supervisor, including options discussed in market commentary such as further capital plans, partnerships or, in extreme cases, restructuring of the licence model.
Phased targets after 2025 (including higher intermediate steps and the final ceiling year) have been adjusted in public policy debate during 2026. Banks should follow the current CBK and Treasury timetable, not outdated step tables alone.
Which Banks? What the Report Does Not Do
The Bank Supervision Annual Report 2025 states that seven banks missed the KSh 3 billion core capital minimum. It does not publish those seven names in the capital-adequacy breach summary cited by CBK and by same-day news reports.
Earlier 2025–2026 industry tracking and quarterly disclosures had repeatedly listed smaller or distressed names working below or near the line, including institutions such as Consolidated Bank of Kenya, Credit Bank, Development Bank of Kenya and Access Bank Kenya, among others that were still raising capital or pursuing mergers. Those names reflect prior public capital-gap reporting. They are not an official CBK roll-call of the seven year-end violators in the 2025 annual report text itself.
Readers should not treat any unofficial list as a confirmed CBK naming of the seven until the regulator or the banks themselves disclose it.
What Happens Next
Undercapitalised banks typically need one or more of:
- fresh equity from shareholders or new investors;
- rights issues or private placements;
- mergers or acquisitions into stronger groups;
- in some state-linked cases, Treasury support discussions.
CBK has previously said it engages non-compliant banks on capital plans and has, at times, stressed limited appetite for open-ended grace periods once a deadline has passed. Enforcement tools remain with the supervisor under the Banking Act and prudential guidelines.
Depositors in Kenya’s banking system continue to rely on the wider sector’s strong average capital and liquidity ratios. Individual weak banks are a supervision issue, not a signal that the whole industry is undercapitalised.
Read also:Tier 1, 2, and 3 Banks in Kenya (2026 List)
Bottom Line
CBK’s 2025 supervision report confirms seven commercial banks finished the year below the KSh 3 billion core capital floor, with further breaches on total capital, core capital and deposit-ratio tests. The sector average still looks solid; the pressure sits on a minority of smaller lenders that must raise capital, merge or restructure under ongoing CBK oversight.
The report does not list the seven by name in the cited breach summary. Watch for bank-by-bank disclosures, capital raises and any follow-up supervisory action as the higher capital roadmap continues.
Sources:
CBK – Bank Supervision Annual Report 2025 (PDF);
People Daily – 7 banks failed to meet Ksh3B capital rule in 2025 – CBK (22 September 2026).
This article is for information only and is not investment or legal advice. Capital figures and compliance status can change as banks raise equity or restructure.