
Key takeaway: A Kenyan Money Market Fund (MMF) pools savers’ cash into short-term, low-risk instruments under CMA rules. A fund manager invests; a bank custodian holds assets; a trustee oversees the manager. You earn a daily-moving yield (industry average recently about 9.2%–9.3% gross), pay about 15% withholding tax on interest, and can usually withdraw in a few working days.
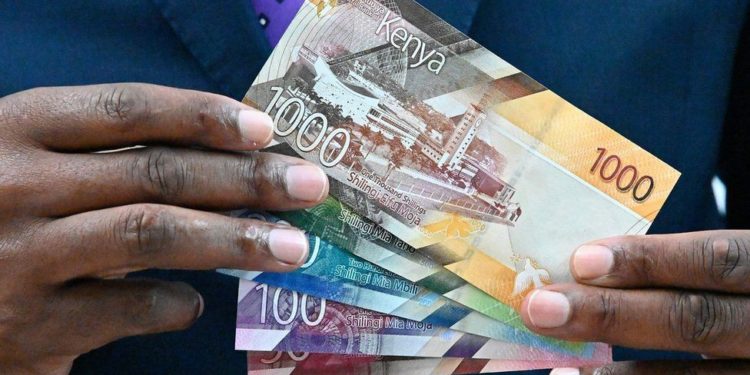
In plain terms, an MMF is a regulated collective investment scheme. Thousands of people put money into one pot. A licensed manager invests that pot in short-term debt such as Treasury bills, bank deposits and approved commercial paper. You own units in the fund, not a personal fixed deposit with the government.
That structure is why MMFs usually beat ordinary savings accounts on yield while still aiming for capital preservation and liquidity. It is also why they are not the same as a bank deposit guaranteed by deposit insurance.
The Four-Party Structure (Why It Matters)
Every legitimate Kenyan MMF sits under a split of roles so one party does not control everything.
Mobile: Swipe left / right → ←
| Role | What they do |
|---|---|
| Fund manager | CMA-licensed firm that decides how the portfolio is invested within the fund mandate |
| Custodian | Usually a commercial bank that safekeeps the fund’s assets; the manager does not keep investor assets in its own pocket |
| Trustee | Independent watchdog that protects unitholders’ interests and monitors compliance with the trust deed and rules |
| Auditor | Independent firm that reviews the fund’s books |
| Regulator | Capital Markets Authority (CMA) licenses and oversees the scheme |
← Swipe on mobile →
Before you invest, check that the product is a real CMA-authorised unit trust and note who the manager, trustee and custodian are. Unlicensed “MMFs” or chat-based schemes promising fixed 20%–30% a month are a different animal. The CMA has repeatedly warned the public about unlicensed investment platforms.
Where the Money Goes
Managers are limited to short-term, relatively liquid instruments so the fund can meet redemptions and keep risk low. Typical holdings include:
Mobile: Swipe left / right → ←
| Asset | What it is | Risk (relative) |
|---|---|---|
| Treasury bills | Short-term government paper (often 91, 182 or 364 days) | Very low credit risk |
| Bank fixed / call deposits | Deposits with commercial banks, often at wholesale rates | Low (bank credit risk applies) |
| Commercial paper / approved notes | Short-term debt of rated companies, where allowed | Low to moderate |
Exact mix and maturity limits sit in each fund’s trust deed and factsheet.
Weighted average maturity is kept short (many funds operate with an 18-month-style outer framework for money-market style portfolios, but you should read the specific fund documents). That short tenor is what supports liquidity compared with long bonds or equity funds.
How Yields, Fees and Tax Work
Interest: Performance is usually calculated daily. Many funds credit or reinvest earnings on a monthly cycle by increasing your units. Published rates move with T-bill yields, deposit rates and the Central Bank’s policy stance.
What “current average” means in late 2026: Independent rankings in September 2026 put the industry average gross effective annual yield around 9.2%–9.3% (for example about 9.3% on mid-September tables and about 9.25% on a 21 September 2026 Serrari index print). Individual funds still range widely, from low single digits to low double digits.
Management fee: Managers typically charge about 1.5%–2.5% a year (around 2% is common). In practice, the yield you see advertised is often already after the management fee, but still before tax. Always read the factsheet wording.
Withholding tax: Interest earned by residents is generally subject to 15% withholding tax, usually treated as a final tax on that income. A 10% gross headline is not what you take home. Rough net ≈ gross × 0.85, before any other personal tax situation your adviser may flag.
Compounding: Leaving units to reinvest is how balances grow over months. Withdrawing monthly interest for spending stops that compounding.
Liquidity: Top-Ups and Withdrawals
Unlike a fixed deposit, most Kenyan MMFs do not lock you in for six or twelve months. You can usually top up by bank transfer, app or M-Pesa (where the manager supports it).
Withdrawals are not always same-day M-Pesa instant cash. Many funds process redemptions in about one to three working days, depending on cut-off times and the manager’s procedures. Some products may have short initial restrictions; check the offer document rather than assuming universal “24–48 hours.”
Plan emergency money with that processing lag in mind.
MMF vs Savings Account vs T-Bill
- Savings account: Instant access, often lower interest, deposit-protection regime differs from unit trusts.
- MMF: Pooled professional management, usually higher yield than basic savings, redemption in working days, CMA unit-trust rules.
- T-bills (direct): You buy government paper yourself (higher minimums via CBK/invest platforms), different tax treatment for individuals on some government securities, less “set and forget” than an MMF.
An MMF is a convenience wrapper around money-market instruments, not magic.
Risks You Should Not Ignore
- Rate risk: When policy rates fall, MMF yields usually ease.
- Inflation: If net yield sits near or below inflation, real purchasing power can stagnate.
- Credit / portfolio risk: Low risk is not zero risk. Bank deposits and commercial paper still carry counterparty risk.
- Liquidity timing: You may wait several working days for cash.
- Operational and conduct risk: Reduced by custodian, trustee, audit and CMA oversight, not eliminated.
- Fraud risk outside the system: Fake apps and unlicensed “funds” remain a real threat.
Do not treat any MMF as a guaranteed fixed rate or as risk-free principal insurance.
How to Choose a Fund
- Confirm CMA licensing and official manager contacts.
- Compare recent yield on the same basis (gross EAR vs daily rate vs net after tax).
- Check minimum investment and top-up size.
- Read fee, trustee, custodian and redemption timeline on the factsheet.
- Prefer managers who publish clear statements and factsheets.
- Match the fund to your goal: emergency cash, business float, or short parking before a larger investment.
Examples of well-known CMA-space managers Kenyans often compare include NCBA, CIC, Britam, SanlamAllianz, Old Mutual, KCB, Equity, Cytonn, Nabo, Etica and others. Ranking by yield changes every week. Convenience of your bank’s app is not the same as the best rate.
How to Start (Typical Path)
- Pick a licensed manager and product.
- Complete KYC (ID, KRA PIN, sometimes photo and bank details).
- Open the unit trust / MMF account via app, USSD, portal or branch.
- Fund with at least the minimum (can be as low as a few hundred or a few thousand shillings depending on the fund).
- Keep statements; track units and yield; withdraw through official channels only.
Related:10 Best Money Market Funds in Kenya in 2026: Yields, Minimums & How to Choose
Frequently Asked Questions
What is a money market fund in Kenya?
A CMA-regulated unit trust that invests pooled money in short-term, interest-bearing instruments.
How do MMFs make money?
From interest and discount income on T-bills, deposits and other approved short-term securities, after fund costs.
Is my money safe?
Structure and regulation reduce risk; they do not make returns or principal risk-free. Use only licensed managers.
How is interest calculated?
Usually daily, with monthly compounding or unit allocation. Confirm on your fund’s documents.
What tax applies?
Generally 15% withholding tax on interest for residents.
How long do withdrawals take?
Often about 1–3 working days; check your specific fund.
What is a good MMF rate in 2026?
The field average has recently been around 9% gross. Top funds can print low double digits; some bank-affiliated funds sit lower. Compare net of tax.
Can I invest with M-Pesa?
Many managers accept M-Pesa or bank transfer. Use only official paybill details from the manager.
MMF vs SACCO?
Different legal form, liquidity, return type (interest/units vs dividends/interest) and risk. Compare both on your own goals.
Bottom Line
Money market funds work in Kenya by pooling retail cash into short-term securities under a CMA framework of manager, custodian, trustee and auditor. You get professional access to money-market yields, daily-moving rates, typical working-day liquidity and a standard 15% tax on interest.
They suit emergency funds and short-term parking better than long-term stock-style growth. Check licensing, fees, redemption rules and net-of-tax yield before you move money, and ignore anyone promising fixed sky-high returns on WhatsApp.
Sources
- Capital Markets Authority (CMA)
- Serrari Group – Kenya MMF rates and average index
- MMFs Kenya – industry yield rankings (September 2026)
- Kenya MMF Calculator – how MMFs work (guide)
- Fund factsheets and offer documents from individual CMA-licensed managers
Investment products carry risk. Yields change and are not guaranteed. This guide is for information only and is not investment, tax or legal advice. Confirm all terms with a licensed fund manager and, where needed, a licensed adviser.