

If you have ever applied for a loan in Kenya, chances are a Credit Reference Bureau already has a file on you. Understanding how these bureaus work could save you from a rejected loan application down the line.
Kenya has exactly three licensed Credit Reference Bureaus, all regulated by the Central Bank of Kenya. This guide covers what each one does, how to check your own report for free, and what your rights are if something on your file looks wrong.
Overview: What CRBs Actually Do
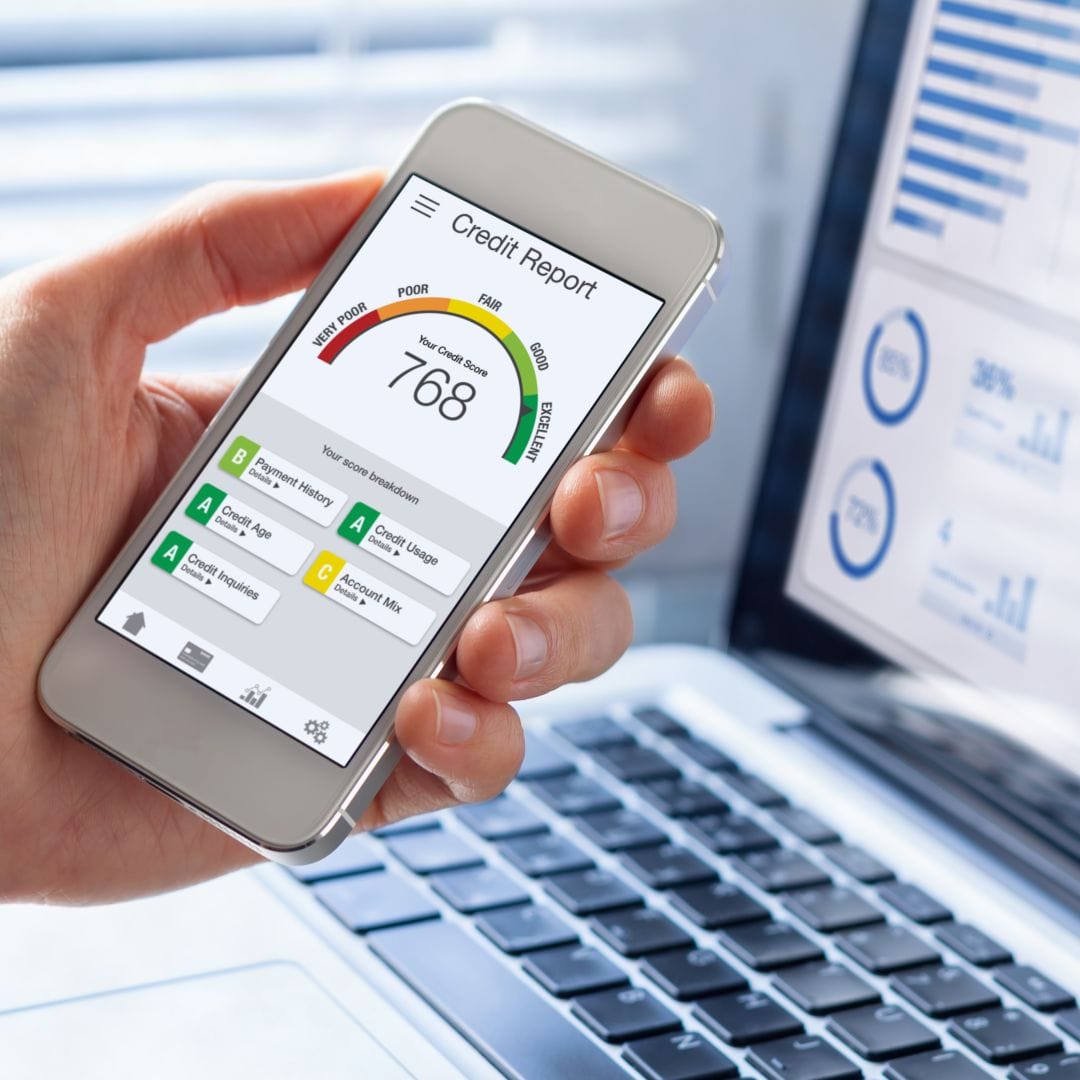
Credit Reference Bureaus collect and manage credit information to help banks, SACCOs, and microfinance institutions assess how risky a borrower is before approving a loan. All CBK-licensed digital lenders, including Tala, Branch, M-Shwari, KCB M-Pesa, and Zenka, are required to report your repayment history to at least one bureau.
Your credit history can actually differ slightly between the three bureaus, depending on which specific lenders report to which bureau, so checking all three gives you the most complete picture of your standing.
The Three Licensed CRBs in Kenya
TransUnion Kenya, formerly known as Credit Reference Bureau Africa, became Kenya’s first licensed bureau on February 9, 2010. The company operates across multiple African nations and offers credit scoring, credit reporting, debt management services, and consumer risk analytics. TransUnion uses a scoring scale from 0 to 999, with 680 and above generally considered a good score.
Metropol CRB traces its roots back to a business information firm established in Kenya in 1966, though it officially received its CBK bureau license in 2011. Metropol specializes in credit information sharing, alternative data sourcing, and issuing official Certificates of Clearance. It uses the Crystal Ball scoring model, ranging from 200 to 900, with 600 and above considered good.
Creditinfo Kenya became the third and most recent bureau licensed in the country, receiving approval on April 29, 2015. Part of a global credit bureau network operating across 15 other countries, Creditinfo focuses on credit risk management, process automation, credit monitoring, and customized credit scorecard development for lenders.
How to Check Your Credit Report
Every Kenyan citizen has the legal right to one free credit report per year from each of the three bureaus, giving you three free checks annually in total. Checking your own report counts as a soft inquiry and does not affect your score, unlike a hard inquiry triggered by an actual loan application.
- TransUnion: Check through their mobile app, website, or SMS tools like Nipashe
- Metropol: Dial the USSD shortcode *433#, use their website, or download the Metropol Crystobol app
- Creditinfo: Register on the Creditinfo Kenya portal for your credit history and real-time monitoring alerts
Since each free check is only valid once per year, consider spreading your checks throughout the year, for example TransUnion in January, Metropol in May, and Creditinfo in September, so you have more frequent visibility into your status.
Understanding Your Credit Score
Generally, a score above 650 is considered good across most Kenyan lenders and qualifies you for better loan terms, while scores below 400 typically result in rejected applications. Negative listings for defaulted loans remain on your file for five years from the date of default, even after you settle the debt, though the status changes from non-performing to settled.
Even small missed payments, sometimes as little as KES 50, can show up on your report and affect your score, so it is worth taking every active loan seriously regardless of size.
Your Rights: Dispute Resolution
If you spot an error on your credit report, you have the legal right to file a dispute directly with the bureau that issued it. The bureau will provide you with a dispute form to detail the incorrect information, then forward your complaint to the lending institution that originally reported it.
The lending institution is legally required to investigate and respond within 14 days, confirming whether the information is correct and should remain, incorrect and should be deleted, or simply outdated and needs updating. If a lender fails to update your status within the required timeframe after you settle a debt, you can file a direct dispute with the bureau to force the correction.
What Happens if You Have a Negative Listing
If you find yourself listed negatively, the first step is checking all three bureaus, since lenders may report to different ones and your listing might not appear everywhere. Contact the original lender directly and negotiate a settlement, since many accept partial payments, often between 50 and 80 percent of the total owed, to close out the account.
Always get your clearance confirmation in writing. After payment, the lender is legally required to update your status from non-performing to settled within 30 days under CBK regulations, so check your report again after that window to confirm the correction actually went through.
Read also:Metropol CRB Kenya — Credit Reports, Scores & Clearance Certificate | Business Listings Kenya
Frequently Asked Questions
How many licensed Credit Reference Bureaus operate in Kenya?
Kenya has exactly three CBK-licensed CRBs: TransUnion Kenya, Metropol CRB, and Creditinfo Kenya.
How many free credit reports am I entitled to each year?
You are legally entitled to one free credit report per year from each of the three bureaus, totaling three free reports annually.
How long does a negative listing stay on my credit report?
Negative listings remain for five years from the date of default, though settling the debt changes the status to settled rather than removing it entirely.
What is the deadline for a lender to respond to a credit dispute?
Lenders are legally required to investigate and respond to a dispute within 14 days of it being filed with the bureau.
Does checking my own credit report lower my score?
No, checking your own report is a soft inquiry and does not affect your score. Only loan applications, which trigger hard inquiries, can temporarily lower it.
Understanding how Kenya’s three Credit Reference Bureaus work puts you in a much stronger position when applying for loans or resolving errors on your file. Checking your report regularly, disputing mistakes promptly, and settling any negative listings quickly all go a long way toward keeping your credit history clean.
With three free checks available annually across TransUnion, Metropol, and Creditinfo, there is really no reason not to stay on top of your credit standing throughout the year.